Best Credit Card for Rent Payment in India (2026)
17 November 2026
I have used credit cards for 20 years, and for the last 8 of them I have not paid for a flight, a hotel, forex markup, or service fees because of how I use my cards. That experience taught me a simple truth: paying rent with a credit card is rarely about direct rewards anymore, and anyone who says otherwise is selling something. Today, the best credit card for rent payment is usually the one that turns your monthly rent into a fee waiver, a milestone unlock, or an interest-free cash flow tool — and sometimes, if you pick carefully, a small reward on top.
If you are in a hurry: for most renters, the IDFC FIRST SWYP Credit Card is the only card that still gives direct value on rent, while premium cards like the HDFC Infinia Credit Card or Axis Magnus Credit Card work only for high-rent profiles chasing milestones. But the right pick changes sharply with your rent amount and why you want to use a card in the first place.
| Rank | Card | Best for | Annual fee |
|---|---|---|---|
| 1 | IDFC FIRST SWYP | Direct rewards on rent without high fees | ₹499 |
| 2 | HDFC Infinia | High rent + milestone fee waiver and premium perks | ₹12,500 |
| 3 | Axis Magnus | High rent + travel milestone rewards | ₹12,500 |
| 4 | SBI Card ELITE | Moderate rent + fee waiver and milestone vouchers | ₹4,999 |
| 5 | Amex Platinum Travel | Rent + travel milestone vouchers (Amex acceptance needed) | ₹5,000 |
| 6 | HSBC Premier | Very high rent + global elite status | ₹20,000 |
| 7 | HDFC Regalia Gold | Mid-range rent + all-round benefits and fee waiver | ₹2,500 |
| 8 | Kotak League Platinum | No-fee simplicity for low rent | ₹499 (waivable) |
IDFC FIRST SWYP is the only card with direct value on rent transactions. HDFC Infinia and Axis Magnus are premium cards where rent counts toward big milestones, not rewards. SBI Card ELITE and HDFC Regalia Gold are mid-tier options where rent helps waive the fee. Amex Platinum Travel works only if your platform accepts Amex, and HSBC Premier is for those already in that banking relationship. Kotak League Platinum is a fee-free fallback.
Why Pay Rent with a Credit Card?
Rent is usually the largest monthly expense for an Indian household, and putting it on a credit card can feel like a shortcut to easy rewards. The reality is more nuanced, but there are still four solid reasons to do it.
- Cash flow management. If your salary comes after the first week of the month and your rent is due on the first, a credit card gives you 45-50 days of interest-free credit. That is the oldest reason to use a card, and it still works.
- Meeting spend milestones. Premium cards waive their fee or unlock vouchers, points, or status once you cross annual (or monthly) spending thresholds. Rent can be a huge accelerator, as long as the card counts rent toward those thresholds.
- Fee waiver on mid-tier cards. Cards like HDFC Regalia Gold or SBI Card ELITE have annual fees that are waived if you spend a certain amount. Rent can push you over that line without extra effort.
- Building credit history. For young renters, paying rent through a credit card and clearing the bill on time is a legitimate way to build a CIBIL score, especially if you cannot get a card for other purposes yet.
What you should not expect is direct reward points on rent. Most banks in India have excluded rent from reward earning in the last two years, and only a handful of exceptions remain. The best credit card for rent payment in 2026 is usually the one that gives you an indirect benefit, not a direct reward.
How Rent Payment via Credit Card Works
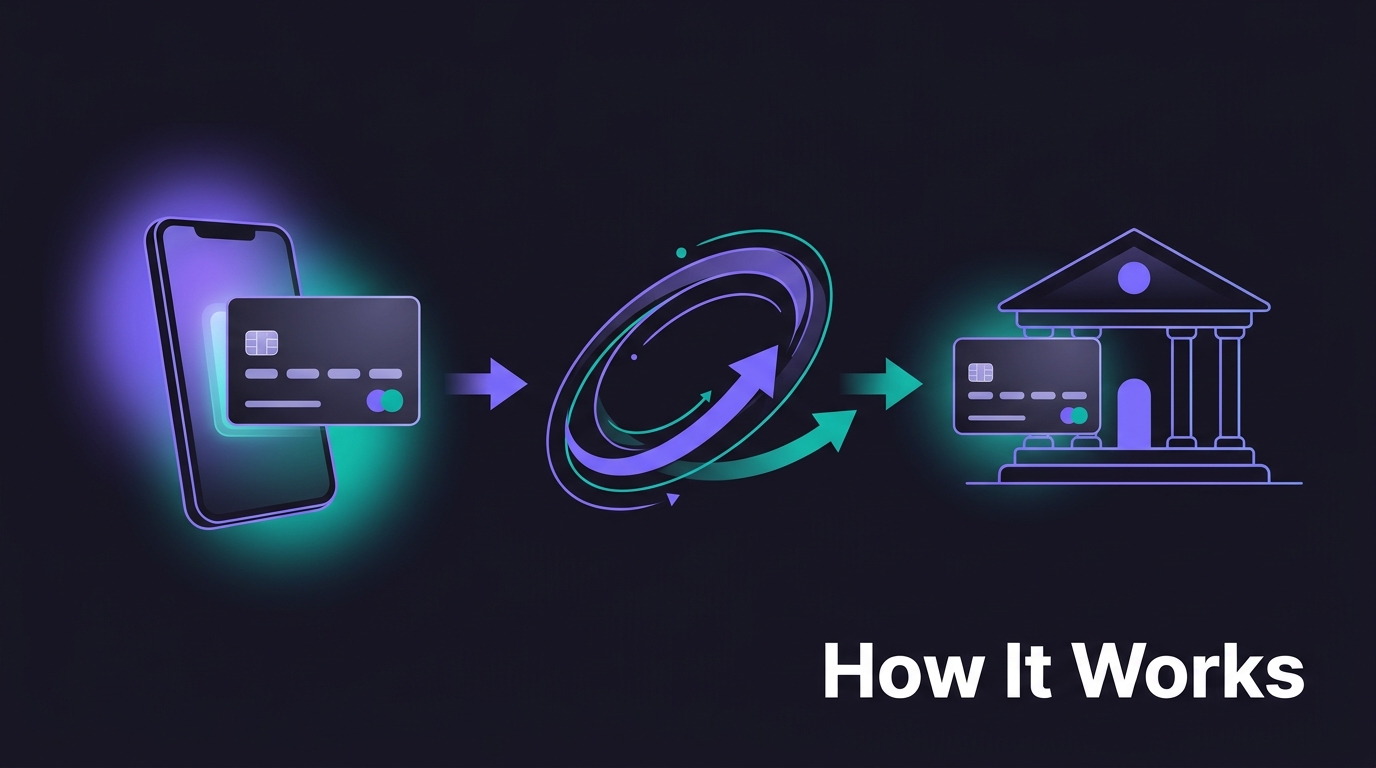
You cannot pay rent directly to a landlord using a credit card unless the landlord has a business and a card terminal. Instead, you use a rent payment platform that charges your card and then transfers the money to the landlord’s bank account.
The flow looks like this:
- You enter your rent details and landlord’s bank details on a platform.
- The platform charges your credit card for the rent amount plus a processing fee.
- The platform transfers the rent amount to your landlord’s bank account within 1-2 working days.
- You pay your credit card bill when it is due, which also covers the processing fee.
Popular platforms include RedGiraffe, NoBroker Pay, RentenPe, Housing.com, and BharatNXT. Each has a slightly different fee structure, and some charge an additional convenience fee for credit cards compared to debit cards or bank transfers.
Direct bank transfer from credit card to landlord is not allowed for residential rent in India, so those platforms act as the middleman. That middleman fee is the crux of the math: if the fee is 1-2% + GST and your card gives you nothing in return, the transaction is a loss. Only use a card when the net benefit is positive or you genuinely need the credit period.
The Best Credit Cards for Rent Payment
The "best" card depends on your rent amount and what you want from the payment. Below is a ranking that covers the most practical options, from direct reward cards to pure milestone cards. I have ranked them based on everyday usefulness for an Indian renter, not just premium status.
1. IDFC FIRST SWYP Credit Card
Why it earns the top spot: It is the only card I can confidently call the best credit card for rent payment for most people. Unlike premium cards, it gives direct value on rent transactions, and it is not loaded with high fees. For renters paying up to ₹40,000 a month, the reward rate usually offsets the platform fee, leaving you either break-even or slightly positive.
Who it suits: Budget-conscious renters, first-time card users who rent, and anyone who wants a straightforward card without chasing spend milestones.
Key benefits: Direct rewards on rent (though exact rates and caps can change, so verify current terms on the issuer’s website), a lifetime-free structure for many users, and a modest annual fee of ₹499. The card is known for being friendly to low- and mid-income profiles.
Honest drawback: The reward rate may be capped or conditioned, and the card’s benefits beyond rent are ordinary. It is not a premium lifestyle card. Also, if your rent is high, the cap might leave a large portion of the payment without any reward.
Fee: ₹499 per year (often waived).
Need more details? Read my full breakdown of the IDFC FIRST SWYP Credit Card.
2. HDFC Bank Infinia Credit Card
Why it is ranked here: Infinia gives no direct rewards on rent, period. But rent payments count toward the annual spend milestone of ₹10 lakh, which waives the ₹12,500 renewal fee. If you already spend a lot on this card, adding rent can push you over the milestone and unlock the fee waiver, plus you get strong lounge access, travel benefits, and a very high credit limit for cash flow.
Who it suits: High-income professionals with rent above ₹80,000 per month who already want Infinia for its premium benefits and are willing to pay platform fees to reach milestones.
Key benefits: Unlimited lounge access, 10X reward points via SmartBuy, milestone bonuses, and the fee waiver on ₹10 lakh annual spend. The high credit limit means a single rent transaction does not destroy your utilisation ratio.
Honest drawback: It is invitation-only, so you cannot just apply. The annual fee is steep if you do not hit the waiver. And the platform fee you pay to route rent through Infinia must be justified by the milestone value you unlock; if you miss the milestone, you have lost money.
Fee: ₹12,500, waived on ₹10 lakh annual spend.
More about this card: HDFC Infinia Credit Card.
3. Axis Bank Magnus Credit Card
Why it is ranked here: Magnus is a favourite among travel hackers because monthly and annual milestones unlock premium reward rates and transfer ratios to airline and hotel partners. Rent payments, though not earning base rewards, count toward those milestones. If your rent is above ₹1.5 lakh per month, the 35 points per ₹200 above that threshold is very attractive, and rent can help you hit that.
Who it suits: Travel enthusiasts who pay high rent and want to convert large spends into air miles and hotel points, especially those already using Axis cards for travel.
Key benefits: 12 EDGE points per ₹200 up to ₹1.5L monthly spend, then 35 points per ₹200 above that; 5X via Travel EDGE; unlimited domestic and international lounge access; fee waiver on ₹25 lakh annual spend.
Honest drawback: Recent devaluations have changed milestone structures, so you must verify current terms before relying on rent for milestones. The fee is high, and if your rent is below ₹1.5 lakh, you get only the base milestone behaviour, which may not justify platform fees. Also, the reward value depends on your ability to redeem for travel, which not everyone wants.
Fee: ₹12,500, waived on ₹25 lakh annual spend.
Read my notes on the Axis Magnus Credit Card.
4. SBI Card ELITE
Why it is ranked here: SBI Elite does not give direct rewards on rent, but rent payments count toward the annual spend threshold for fee waiver and, historically, toward milestone bonus reward points. It is a more accessible premium option than Infinia or Magnus, with a lower fee and good lifestyle benefits like lounge access and vouchers.
Who it suits: Salaried individuals with moderate to high rent (₹50,000-₹1,00,000) who want a premium card with realistic fee waiver potential and milestone vouchers without the invitation-only barrier.
Key benefits: Fee waiver on ₹10 lakh annual spend, milestone bonus reward points, airport lounge access, and lifestyle vouchers. The spend requirement is lower than Magnus and similar to Infinia, but eligibility is easier.
Honest drawback: SBI changed its reward structure in 2026, and rent may not earn points at all. The card’s value is heavily tied to milestones, so if your total annual spend is far below ₹10 lakh, the fee is not worth it.
Fee: ₹4,999, waived on ₹10 lakh annual spend.
See my full take on the SBI Card ELITE.
5. American Express Platinum Travel Credit Card
Why it is ranked here: Amex Platinum Travel counts rent payments toward its milestone spends, which unlock significant travel vouchers. For example, reaching ₹1.9 lakh in a year gives 7,500 points, and ₹4 lakh gives an additional 10,000 points plus travel vouchers. If your rent is high and you can route it through a platform that accepts Amex, the milestone value can offset the platform fee and your card fee.
Who it suits: Renters who travel frequently and can leverage milestone rewards for hotel and flight vouchers, especially those already in the Amex ecosystem for other spending.
Key benefits: Milestone-based travel rewards, welcome gift of travel vouchers, and no pre-set spending limit if you have a good history with Amex. The ₹4 lakh milestone is very achievable for renters paying ₹30,000+ per month.
Honest drawback: Amex acceptance on rent platforms is limited; many major platforms do not support Amex. You must first confirm your platform accepts it. Also, Amex cards have lower acceptance generally in India, and the reward vouchers are travel-specific, which is useless if you do not travel.
Fee: ₹5,000 per year.
More on this card: American Express Platinum Travel Credit Card.
6. HSBC Premier Credit Card
Why it is ranked here: HSBC Premier is a relationship-banking product, but it is often mentioned for high-value rent because the spends help meet annual milestones that unlock elite privileges like lounge access, hotel upgrades, and fee waivers. It has a very high credit limit suitable for large rent transactions, and the forex markup is excellent if you have international expenses.
Who it suits: High-net-worth individuals with very large rent payments who already have or can get HSBC Premier banking status and want global benefits.
Key benefits: Unlimited domestic and international lounge access, 0.99% forex markup, welcome points, and high credit limits. The card is designed for top-tier spenders, and rent can be a useful tool to maintain status.
Honest drawback: You cannot simply apply; you need an existing HSBC Premier banking relationship with qualifying balance, salary credit, or mortgage route. The annual fee is ₹20,000, and rewards on rent are capped per month. For most renters, this is overkill and inaccessible.
Fee: ₹20,000 (joining fee ₹12,000).
Reference only: HSBC Premier Credit Card.
7. HDFC Bank Regalia Gold Credit Card
Why it is ranked here: Regalia Gold is a popular mid-tier card that is much easier to get than Infinia and still provides good value. Rent payments count toward the annual spend requirement for fee waiver, and the card offers decent rewards on other categories, lounge access, and travel benefits. For rent up to ₹80,000 per month, it can help you hit the ₹4 lakh annual fee waiver easily.
Who it suits: Mid-range renters who want a well-rounded card where rent helps achieve the fee waiver and some milestone rewards without paying a premium fee.
Key benefits: Fee waiver on ₹4 lakh annual spend, 12 domestic and 6 international lounge visits per year, complimentary Club Vistara Silver and MMT Black Elite memberships, milestone flight vouchers up to ₹10,000 per year, and a low 2% forex markup.
Honest drawback: Rent does not earn reward points; it only counts toward the fee waiver and possibly some milestones. The platform fee must be less than the value you get from the waiver, which usually means you need to spend at least ₹4 lakh overall anyway.
Fee: ₹2,500, waived on ₹4 lakh annual spend.
Read my analysis of the HDFC Regalia Gold Credit Card.
8. Kotak League Platinum Credit Card
Why it is ranked here: Kotak League Platinum is a lifetime-free entry-level card (fee waivable). It gives no direct rewards on rent, but there is no annual fee to recover, and it can be used on rent platforms where fees are low. It provides interest-free credit for 45-50 days, which is useful for cash flow. For someone who does not want to chase milestones or pay high fees, this is a simple option.
Who it suits: Budget-conscious renters who want a no-fee card that can still be used for rent payments without any pressure to hit spend targets, or those building credit history.
Key benefits: Lifetime free (fee waived on ₹50,000 annual spend), 8X reward points on travel agencies, airlines, electronics and department stores, free PVR tickets or 10,000 points every 6 months on ₹1.25L spend, and a low forex markup for a basic card.
Honest drawback: No rent-specific benefits, and the reward structure is not designed for rent. The card’s benefits are ordinary, and the only real reason to use it for rent is the credit period.
Fee: ₹499, waived on ₹50,000 annual spend.
How to Choose the Right Card for Your Rent
There is no single best credit card for rent payment; the right one depends on your rent amount, your spending goals, and your tolerance for platform fees. Here is how I think through it.
1. Assess your monthly rent amount.
- Low rent (below ₹30,000): You are unlikely to hit high milestones, so a direct reward card like IDFC FIRST SWYP or a fee-waiver card like Kotak League makes sense. Avoid high-fee premium cards unless you have other large expenses.
- Mid rent (₹30,000-₹80,000): You can hit fee waiver thresholds on cards like HDFC Regalia Gold or SBI Elite. Platform fees add up, so calculate whether the waiver and rewards on other spending justify it.
- High rent (above ₹80,000): You are in milestone territory for Infinia, Magnus, or Amex Platinum Travel. These cards can deliver strong value if you already use them for other premium benefits.
2. Decide your goal.
- Direct cashback or rewards: Only IDFC FIRST SWYP offers this on rent now (with caveats).
- Fee waiver on a card you already have: Pick the card with the most achievable spend threshold relative to your rent. Regalia Gold’s ₹4 lakh is much easier than Infinia’s ₹10 lakh.
- Travel rewards: Magnus and Amex Platinum Travel are the strongest, but you must value travel vouchers and be able to use them.
- Building credit: Use a no-fee card and pay the bill in full; rent payments reported to CIBIL can help.
3. Factor in platform fees and bank surcharges.
Most platforms charge 1-2% + GST on credit card rent payments. Some banks levy an additional 1% surcharge on top, though this is rare for rent platforms. Always calculate the net benefit: if the platform fee is 1.5% and your card gives you 1.5% in rewards or milestone value, you break even. If it gives less, you are paying extra for credit, which is sometimes worth it for cash flow.
4. Check the fine print.
Before you commit, verify on the card issuer’s website whether rent transactions are excluded from rewards and whether they count toward milestone spends. This changes frequently, and what was true six months ago may not be true today.
If you are unsure which profile you fit, take the 2-minute card quiz and I will point you to the one card that fits your rent and spending.
What Are the Costs Involved?
Let me break down the typical charges when you pay rent with a credit card through a platform, because ignoring them is the quickest way to lose money.
- Platform fee: Usually 0.5% to 2% of the rent amount, plus GST. RedGiraffe often charges around 0.7-1%, NoBroker and RentenPe around 1-2%. Always check the exact fee for credit cards, as some platforms charge more for credit than for debit or netbanking.
- Bank surcharge (rare): Most Indian banks do not add a surcharge on rent platform transactions, but a few may treat it as a utility or service payment and add 1%. Check your card’s terms.
- GST: 18% is charged on the platform fee, not the rent amount.
Example calculation for ₹50,000 rent:
- Rent: ₹50,000
- Platform fee (say 1.5%): ₹750
- GST on fee (18%): ₹135
- Total paid via card: ₹50,885
- Your card’s reward or milestone value: must be at least ₹885 to break even. For a card giving no direct rewards but counting toward a fee waiver, you need to value the waiver at that level.
If you pay the bill in full, the platform fee is your only cost. If you do not pay in full, credit card interest of 40%+ APR dwarfs any benefit. Paying rent with a card only makes financial sense when the fee is offset by rewards, milestone value, or genuine cash flow need.
Common Mistakes to Avoid
I have seen renters make these mistakes too often, and they can turn a smart move into a costly one.
- Carrying a balance. If you do not pay the credit card bill in full, the interest will erase any benefit and then some. Never use a card for rent if you cannot clear the bill.
- Ignoring credit utilisation. A single rent payment can be a large portion of your credit limit. If your utilisation jumps above 30% of the limit, your CIBIL score can dip temporarily. This is especially risky with low-limit cards.
- Using a card that gives nothing and paying high platform fees. If your card excludes rent from rewards and you are not hitting any milestone, the platform fee is pure loss. Use a cheaper payment method.
- Forgetting landlord PAN requirements. For rent above ₹50,000 per month, you are required to report the landlord’s PAN to the tax authorities. Credit card payment does not change this, and platforms may ask for it.
My Personal Take (from 20 Years of Using Cards)
I do not use credit cards for rent to earn points on the rent itself. I use them because rent is a large, predictable monthly expense that can help me hit annual spend thresholds on premium cards, which then waive the fee and unlock benefits I actually use — airport lounges, flight vouchers, and travel transfer partners. That is where the real value is, and I have done this for years.
I have also learned that the rent payment landscape changes quickly. Banks silently remove rent from reward eligibility, platforms raise fees, and milestones get restructured. What worked for me last year may no longer work this year, so I re-evaluate every few months. My advice is to be ruthless about the math: calculate the platform fee, estimate the milestone or reward value, and only use a card when the net is positive or you truly need the credit period.
For most renters, the IDFC FIRST SWYP Credit Card is the best credit card for rent payment because it gives direct value without a high annual fee. If you are in the premium tier, use your rent as a milestone tool on a card you already hold, not as a reason to get a new premium card.
Fees, reward rates, and platform charges change frequently, so always confirm the latest terms on the bank’s website before applying or making a rent payment.
Frequently Asked Questions
Can I pay house rent using a credit card in India?
Yes, but not directly to the landlord. You use an intermediary platform like RedGiraffe, NoBroker, RentenPe, or Housing.com, which charges your card and transfers the amount to the landlord. A processing fee applies.
Do credit cards give rewards on rent payments?
Most cards do not. Banks have excluded rent from reward earning in recent years. The only widely known exception is the IDFC FIRST SWYP Credit Card, which still gives some direct value, but even that may have caps. Premium cards typically count rent only toward milestones, not rewards.
What is the typical fee for paying rent with a credit card?
Platforms usually charge 0.5% to 2% of the rent amount plus 18% GST on that fee. Some banks may add a 1% surcharge, though this is rare for rent. For a ₹50,000 rent, expect to pay roughly ₹500-₹1,200 extra depending on the platform.
Which credit card is best for rent payments in 2026?
For most renters, the IDFC FIRST SWYP Credit Card is the best credit card for rent payment because it offers direct value with a low fee. High-rent payers may prefer premium cards like HDFC Infinia, Axis Magnus, or Amex Platinum Travel for milestone benefits, but only if they already fit those profiles.
Does paying rent with a credit card affect my credit score?
Yes, in two ways. If you pay on time and keep utilisation low, it can help build a positive credit history. If you miss payments or let your utilisation rise above 30% of your credit limit, it can hurt your score. Always keep your total card utilisation in check.
If you want a clear recommendation based on your rent amount and spending style, find the card made for you. It takes about two minutes, and it is free.

Written by
Chitransh Saxena
20 years of credit card use, and 8 years without paying for a flight, hotel or forex fee. I write CardBuddy's guides.