Best Way to Pay Credit Card Bill for Cashback (2026)
23 October 2026
I have used credit cards for two decades, and for the last eight years, I have not paid for a flight, a hotel stay, or a forex markup. That is not because I do not spend; it is because I make every rupee work. One habit that quietly adds up is paying my credit card bill in a way that gives me cashback. If you are looking for the best way to pay credit card bill for cashback, this is my honest, tested take.
Here is the short answer: use a cashback credit card for your regular spends, then pay that card's bill through an app that gives rewards, but always subtract the platform fee. Some apps charge nothing for certain bank cards, and some cards give cashback on the payment itself. I will give you the exact combinations that work for me.
Quick Answer: The Best Cards for Bill Payment Cashback
These are the cards I recommend, ranked for their ability to reward your bill payments and everyday spends. The annual fees below are from our card database, but always confirm on the bank's website before applying.
| Rank | Card | Best For | Annual Fee |
|---|---|---|---|
| 1 | HDFC Bank Millennia Credit Card | Online spenders and frequent bill payers | Rs. 1,000 |
| 2 | Axis Bank ACE Credit Card | Regular utility and bill payments | Rs. 499 |
| 3 | Airtel Axis Bank Credit Card | Airtel users and utility bill payers | Rs. 500 |
| 4 | SBI Cashback Card | Flat-rate cashback on all online spends | Rs. 999 |
| 5 | Amazon Pay ICICI Credit Card | Amazon and UPI users | Rs. 0 |
| 6 | HSBC Live+ Credit Card | Monthly spending with flat rewards | Rs. 999 |
| 7 | Standard Chartered Smart Credit Card | Online shoppers and bill payers | Rs. 499 |
- HDFC Millennia: 5% cashback on Amazon, Flipkart, Swiggy, Zomato and more. It is my top pick for online-heavy spenders.
- Axis ACE: 5% cashback on utility bill payments via Google Pay. If you pay electricity, gas, or phone bills, this one earns its keep.
- Airtel Axis: 25% cashback on Airtel recharges and bills. A no-brainer if you are on Airtel.
- SBI Cashback: 5% flat cashback on all online spends up to Rs. 5,000 per month. Simple and predictable.
- Amazon Pay ICICI: Lifetime free, 5% back on Amazon for Prime members. Great for Amazon loyalists.
- HSBC Live+: 10% cashback on dining, groceries and utilities (capped at Rs. 1,200 per month). Very underrated.
- Standard Chartered Smart: 2% cashback on all online spends, capped at Rs. 1,000 per month. A budget-friendly option.
Want to see how they stack up against each other? Compare cashback cards side by side on CardBuddy.
Why Paying Your Credit Card Bill for Cashback Makes Sense
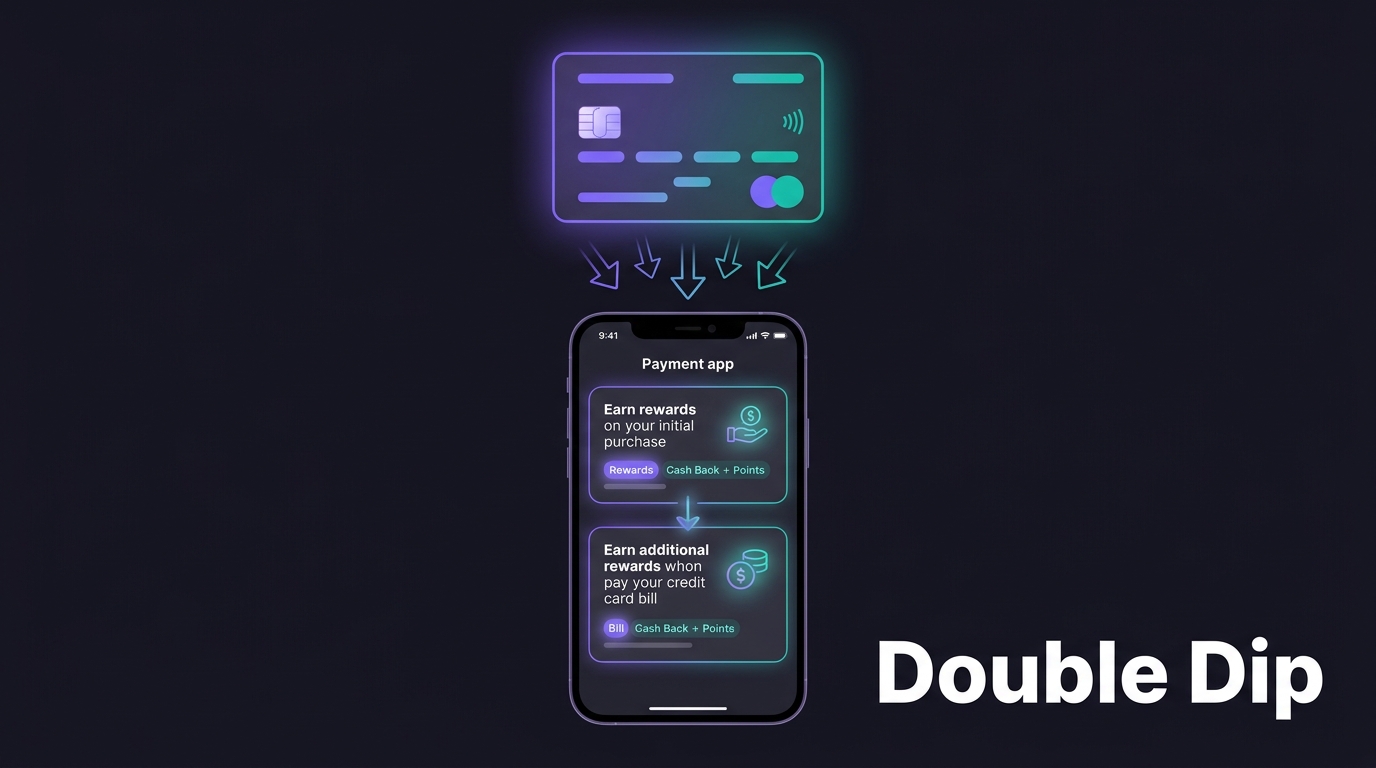
Most people stop at earning rewards on the purchase. Then they pay the bill from a regular bank account and call it a day. That leaves money on the table. The smart move is to earn on the original spend and again on the bill payment. That is double-dipping, and over a year, it adds up.
Even 1% cashback on a bill of Rs. 50,000 per month means Rs. 6,000 a year. That is a nice dinner or a small weekend trip. But the catch is platform fees. Many bill payment apps now charge 1% to 1.18% including GST. If your reward is only 1%, the fee eats it entirely. So the real trick is to find combinations where the reward exceeds the fee, or where the fee is zero.
First, Pick the Right Card for Your Spends
You cannot get bill payment cashback if your card does not give it. Some cards explicitly reward utility or bill payment spends, others give flat cashback on everything, and some exclude certain categories. The seven cards I listed above are a good starting point. The right one depends on where you spend the most. If you are shopping on Amazon, go for the Amazon Pay ICICI or HDFC Millennia. If you pay a lot of utility bills, the Axis ACE or Airtel Axis make more sense. For an all-rounder, the HDFC Millennia is hard to beat.
If you want to explore more cashback cards, check out my list of the best cashback credit cards in India.
Best Bill Payment Apps for Cashback
Once you have a good card, you need to choose how to pay its bill. I have tested many apps, and here is my honest take.
PayZapp
HDFC Bank's own app. It is completely free for HDFC card bill payments, and the settlement is instant. If you have an HDFC card, this is the safest and cheapest way to pay. You may also get occasional cashback offers, but the zero fee is the main benefit.
super.money
This app often offers some cashback on bill payments, but they now charge a platform fee for most cards. You need to calculate whether the cashback beats the fee. For some banks, the fee is lower, and sometimes they run zero-fee promotions. Check the app before paying.
CRED and CheQ
These are popular, but their rewards have become very thin. CRED gives tokens and tiny cashback, while CheQ gives vouchers that barely cover the fee. I rarely use them for cashback now, unless there is a special offer. Both charge a platform fee, and the settlement can take up to a day.
Amazon Pay
I have used Amazon Pay to pay credit card bills, and sometimes you get small cashback or reward points if you use a card that gives rewards on Amazon Pay spends. But Amazon Pay itself charges a fee for credit card bill payments now. Check the fee before paying. It is not always worth it.
My routine is simple: for HDFC cards, use PayZapp. For other bank cards, I use super.money only when the net cashback is positive after the fee. Otherwise, I use the bank's own netbanking or UPI, which is usually free and instant.
I have written a detailed comparison of the best app to pay your credit card bill in India, covering fees, rewards, and settlement speed.
The Stacking Strategy: Earn on the Spend and on the Payment
Here is how I maximise cashback with a typical month: I use my HDFC Millennia card for all online spends, earning 5% on Amazon and 1% on other bills. When the bill comes, I pay it through PayZapp, which costs nothing. That way, I earn on the original purchases and do not lose anything on the payment. If you have a card that gives cashback on the bill payment itself, even better. For example, if you use an Amazon Pay ICICI card to pay another card's bill on Amazon Pay, you may earn 2% on that transaction. But remember, Amazon Pay now charges a fee for credit card bill payments, so the net reward might be low.
Let me show a simple example: suppose you spend Rs. 30,000 on Amazon with the HDFC Millennia card, earning 5% cashback = Rs. 1,500. The bill is Rs. 30,000. You pay it via PayZapp for free. Total cashback this month: Rs. 1,500. If you had used a card with no rewards and paid via an app charging 1.18% fee, you would have earned nothing and paid Rs. 354 extra. The difference is real.
Watch Out for Platform Fees
This is the biggest trap in 2026. Almost every third-party app charges a fee of 1% to 1.18% including GST. That fee can silently eat your cashback. For example, if a card gives 1% cashback on bill payment and the app charges 1.18%, you are losing 0.18%. If the card gives 2% and the fee is 1%, you net only 1%. Always do the math: net cashback = card cashback - platform fee. If the result is zero or negative, use a free method.
Banks' own apps and netbanking are usually free. UPI payments are also free. Settlement is instant with bank methods, while third-party apps may take a few hours to a day. If your due date is near, do not risk it with a slow app.
Which Card Should You Use to Pay the Bill?
Some cards reward the bill payment transaction itself. For example, the Axis ACE Credit Card gives 5% cashback on utility bill payments via Google Pay. If you use that same card to pay an electricity or gas bill, you earn 5%. But if you use it to pay another credit card's bill, the reward may not apply, because the merchant category is different. Always check the card's terms.
The HDFC Millennia Credit Card gives 1% cashback on all other spends, which includes bill payments. The SBI Cashback Card gives 5% on online spends, but bill payments may be excluded or capped. I have verified the SBI card's terms, and utility and bill payments are often in the excluded list. So do not assume; read the fine print.
If you want to know which card is best for your spending, take the 2-minute quiz on CardBuddy.
My Personal Process for Maximum Cashback
I keep it simple. I use the HDFC Millennia card for Amazon and Flipkart orders, which gives 5% cashback. I use the Axis ACE for utility bills, which gives 5%. For everything else, I use the Millennia, which gives 1%. When bills come, I pay the HDFC bill via PayZapp for free, and the Axis bill via UPI or netbanking. I never pay a platform fee unless I am getting more cashback back than the fee, which is rare.
I always pay the full amount on time. That is non-negotiable. Interest charges will wipe out any cashback you earn. I never carry a balance, and I never pay only the minimum due.
For a broader view of payment methods, read my guide on all the ways to pay your credit card bill in India.
Common Mistakes to Avoid
- Paying only the minimum due: That triggers interest at 30-40% per year. No cashback can beat that.
- Ignoring platform fees: As I said, always subtract the fee. A 1% fee can turn a 1.5% reward into 0.5%.
- Chasing rewards and missing the due date: Late fees and credit score damage are not worth a few rupees of cashback.
- Assuming all cards reward bill payments: Many cards exclude utilities or bill payments from cashback. Check the terms.
- Using a card with high annual fee for a small benefit: If you do not spend enough to waive the fee, the math may not work.
Which Card for Which Profile?
Here is my honest recommendation based on your spending habits.
If you want a free card
Get the Amazon Pay ICICI Credit Card. It has no annual fee, gives 5% on Amazon for Prime members, and 2% on Amazon Pay partner merchants. Even if you pay your credit card bill through Amazon Pay and earn 2%, the platform fee might reduce it, but the card itself is still excellent for Amazon spending.
If you spend a lot online
The HDFC Millennia is my top pick. 5% cashback on the biggest e-commerce sites and 1% on everything else. The annual fee of Rs. 1,000 is waived on spends of Rs. 1,00,000, which is easy for online shoppers.
If you pay high utility bills
Go for the Axis ACE. It gives 5% on utility bill payments via Google Pay, 4% on Swiggy, Zomato and Ola, and 1.5-2% on other spends. The fee of Rs. 499 is waived on Rs. 2,00,000 annual spend.
If you are an Airtel user
The Airtel Axis card is a no-brainer. 25% cashback on Airtel recharges and bills, 10% on other utilities. Fee is Rs. 500, waived on Rs. 2,00,000.
If you want flat cashback on everything
The SBI Cashback Card gives 5% on all online spends (up to Rs. 5,000 per month) and 1% offline. But check if your bill payment is in the included category. It has an annual fee of Rs. 999, waived on Rs. 2,00,000.
If you are a student or new to credit
Start with the Amazon Pay ICICI or a lifetime free card. You need a credit score and some income to get approved. The Amazon Pay card has a relatively low income requirement of about Rs. 20,000 per month.
If you travel internationally
None of these cards are low-forex cards. If you travel abroad, you may want a separate card with zero forex markup. I have a detailed guide on the best zero markup forex credit cards in India.
Still not sure? Find the card made for you with our quick quiz.
FAQs
Which app gives the most cashback for credit card bill payment?
There is no single answer because it depends on your card and the fees. super.money often gives cashback but charges a fee. PayZapp is free for HDFC cards. CRED and CheQ give minimal rewards now. I recommend using your bank's app or netbanking for zero fees, unless an app offers a net positive cashback after its fee.
Do I have to pay a platform fee when I pay my credit card bill?
Most third-party apps charge a fee of 1% to 1.18% including GST. Bank apps and netbanking are free. UPI payments are also free. Always check the fee before paying through any app.
Can I earn cashback on my credit card bill payment using another credit card?
Usually not. Most credit cards do not reward payment of another credit card's bill. Some cards may give rewards on 'other spends' but often exclude bill payment or wallet loads. Check your card's terms before doing this.
What is the best way to pay an HDFC credit card bill for cashback?
Use PayZapp. It is free, instant, and you can sometimes get cashback offers. If you are using an HDFC card that gives rewards on bill payment, you may also earn on the payment itself, but check the card's terms.
How does reward stacking work for credit card bills?
Reward stacking means earning twice: first on the purchase with a cashback card, then on the bill payment through an app that gives rewards. The net reward equals card cashback plus app reward minus any platform fee. The goal is to keep that number positive.
Fees and benefits change often, so before you apply for any card or use any app, confirm the current terms on the bank's website.
If you want a card that fits your exact spending, take the 2-minute quiz on CardBuddy. It will match you with the right card, and you can compare cashback cards side by side to see the numbers.
Written by
Chitransh Saxena
20 years of credit card use, and 8 years without paying for a flight, hotel or forex fee. I write CardBuddy's guides.